My mother used to pee in a Styrofoam cup at work because there were no toilets.
Her job? She sat in a wooden parking booth across the street from Flint East - one of General Motors' sprawling manufacturing complexes in Flint, Michigan. She'd gotten the parking attendant job through a family friend who owned those lots. Nearly every car parked there belonged to somebody who worked inside "the shop."
There were two booths. Calling them “booths” probably makes them sound more substantial than they were. The smaller one was basically a wooden box with a window, a desk, two chairs and a wall heater.
I was somewhere between ten and fifteen at the time. My siblings and I would help her patrol the lots on evenings and weekends. One day the rain was coming down so hard outside that tiny booth that Mom didn't want to run across the lot to use the bathroom at the corner bar. She grabbed the Styrofoam cup she got at lunch, popped a squat, did her business, cracked the door, and poured it onto the ground.
I watched the rain carry it away almost instantly. WOOSH!
The larger booth, near the main plant entrance, was a little fancier. It had a back room. By “back room,” I mean a storage closet with a bucket you could use as a toilet.
There was a convenience store across the street called Mac's (amazingly, it's still there!) but they wouldn't let you use the restroom unless you bought something. So Mom bought a Diet Coke every day she worked the big booth.
Mom's job was "simple" on paper: walk the lots, check the license plates against the list of people who'd paid, and tow the ones who hadn't.
Some people tried to game the system by backing their cars in so she couldn't see their plate.
Winter was the worst. Sometimes we were out there digging snow away from bumpers with our hands. Mom's gloves would get soggy pretty quickly, so we were bare-handing it most of the time. We worked fast because the sooner we got the plates checked, the sooner we could get back into the booth with the heater.
Mom had no sympathy for the guys who tried to stiff the parking lot. These people were making “shop money,” as she called it, while she was outside freezing her ass off trying to keep us fed.
She wasn't merciless. If there was a genuine health or family crisis, she'd do what she could to keep them from getting towed. But she had a colorful vocabulary for those - ahem - “motherfuckers” (the most printable option) who tried to park and not pay on the regular. If somebody who hadn't paid came out and found his car was towed, she was almost gleeful about it.
To be clear, General Motors didn't employ my mother. She never appeared in any analysis of GM headcount. She wasn't represented in the plant productivity numbers and she wasn't part of the UAW contract.
Those plant workers made her job possible. Every car in that parking lot represented somebody else's paycheck. And those paychecks created hers. That's how living systems work.
I've started calling this the Consequence Gap: The distance between the people who have the authority to make a decision and the people who have to live with what that decision does.
We tend to think of organizational consequences as direct: close a plant and the people who work there lose their jobs.
But that's only the first ripple.
Mom's job existed because those plant workers had jobs. Other businesses existed because they bought lunches, gas, clothes, homes, and Diet Cokes. Their kids went to local schools. Their families paid taxes. Their paychecks circulated through an ecosystem that extended far beyond GM's payroll.
The farther decision-makers get from those ripples, the easier it becomes to believe the spreadsheet tells the whole story.
It doesn't.
Years later, I ended up working inside Flint East myself. I came in as a temporary administrative assistant during the 1998 strike. My first day, I crossed a picket line.
My father was certified Chevrolet mechanic and had a brief stint working for GM. My grandfather had briefly worked for GM, too. One of them was a "scab" but I can't remember who, neither stayed very long. Crossing that line felt uncomfortable as hell on many levels. But I had a kid to feed. I needed the money. That fact mattered just as much to me as the strike mattered to the people standing outside.
I was supposed to stay a few months. I did good work, so they kept finding places for me for a couple of years.
First the site manager's office. Then Plant 6. Later Plant 2, the Delco operation. Eventually I was supporting several managers as the organization kept restructuring.
Once I was inside, I found myself in a weird, but useful position. As a contractor, management didn't see me as labor. Labor didn't see me as management. So people talked around me.
Executives talked in the offices like I wasn't really there. Shop workers were a little more guarded (because technically I worked for “the man”), but not much.
I listened, because understanding why - the context - has always mattered to me.
Depending on where I stood, I heard two very different stories about the same fight. Management talked about costs they couldn't continue carrying. Workers talked about promises, and what they were owed.
Contemporary reporting from the time reflects that same divide. GM argued that work rules and productivity problems were undermining its competitiveness. Workers feared outsourcing and more jobs moving to outside suppliers or lower-cost plants in Mexico. The Flint strikes became so consequential that most of GM's North American assembly operation was expected to grind to a halt.
Everybody had numbers. Everybody had contracts. Everybody had a case.
And the entire city was living downstream from whatever happened next.
That's the part I think we keep missing when we talk about organizational decisions.
We talk about headcount, labor costs, margins and capacity. All of those numbers are real. I use numbers in my own work. One of my tools is literally called the Enoughness Number. It takes all the things you want and need your life to provide and translates them into an annual income target.
Numbers can help us see reality. The problem starts when we confuse the numbers with what the numbers represent.
A spreadsheet can tell you that eliminating 10,000 jobs saves X dollars. It won't show you 10,000 human ecosystems disappearing at once.
Those people have spouses, children and mortgages. They have favorite restaurants, churches, soccer teams, hairdressers, mechanics, and doctors. They mentor people and take care of aging parents. They buy Girl Scout cookies from the kid next door (or their parent who works with them in the shop). They fall in love, break somebody's heart, make art, volunteer, and have ideas that haven't happened yet.
Every one of them is connected to other people. The consequences don't stop at the factory gate. They radiate like ripples in a pond, baby!
SO, those workers are not simply 10,000 units of labor. That number is only the visible edge of the consequence.
When I worked at Flint East, the Delphi spin-off was coming. The prevailing sentiment I heard inside the plant was basically this:
"GM's keeping the valuable parts and spinning the people (and their pension obligations) into Delphi."
That's how shop workers talked about it.
The actual financial structure was more complicated than the shop-floor shorthand, but their concern about the pensions wasn't imaginary.
Delphi became independent from GM in 1999. According to the U.S. Government Accountability Office, its hourly pension plan was only 69.1% funded that year, while its salaried plan was fully funded.
Delphi entered bankruptcy in 2005. By 2009, the Pension Benefit Guaranty Corporation took responsibility for six Delphi pension plans covering approximately 70,000 workers and retirees. At that point, the hourly plan was underfunded by about $4.5 billion and the salaried plan by about $2.7 billion.
I worked in financial services before moving back to Michigan. I was young, but I knew enough to understand that an underfunded pension was not some abstract accounting problem. At that scale, it was a disaster waiting for people to retire into it.
The old-timers knew it, too. A lot of folks were hoping for a buyout so they could retire before the spinoff and keep GM benefits. People worried about whether they could protect the retirement they'd spent decades earning.
Again: numbers on one side. Lives on the other.
I haven't physically driven past Flint East in years.
The last time I saw it in person, some buildings were empty, but there were still buildings. The parking lots across Dort Highway, where Mom worked decades before, still looked like parking lots.
Today, I pulled it up on Google Maps.
Most of the complex is gone.
Concrete slabs. Vacant land. Trees growing through cracks in the remaining foundations where factories once stood. Not just shrubs - trees!
A tree doesn't grow through an industrial foundation overnight. A tree means time. It means nobody disturbed that patch of ground long enough for nature to start reclaiming it.
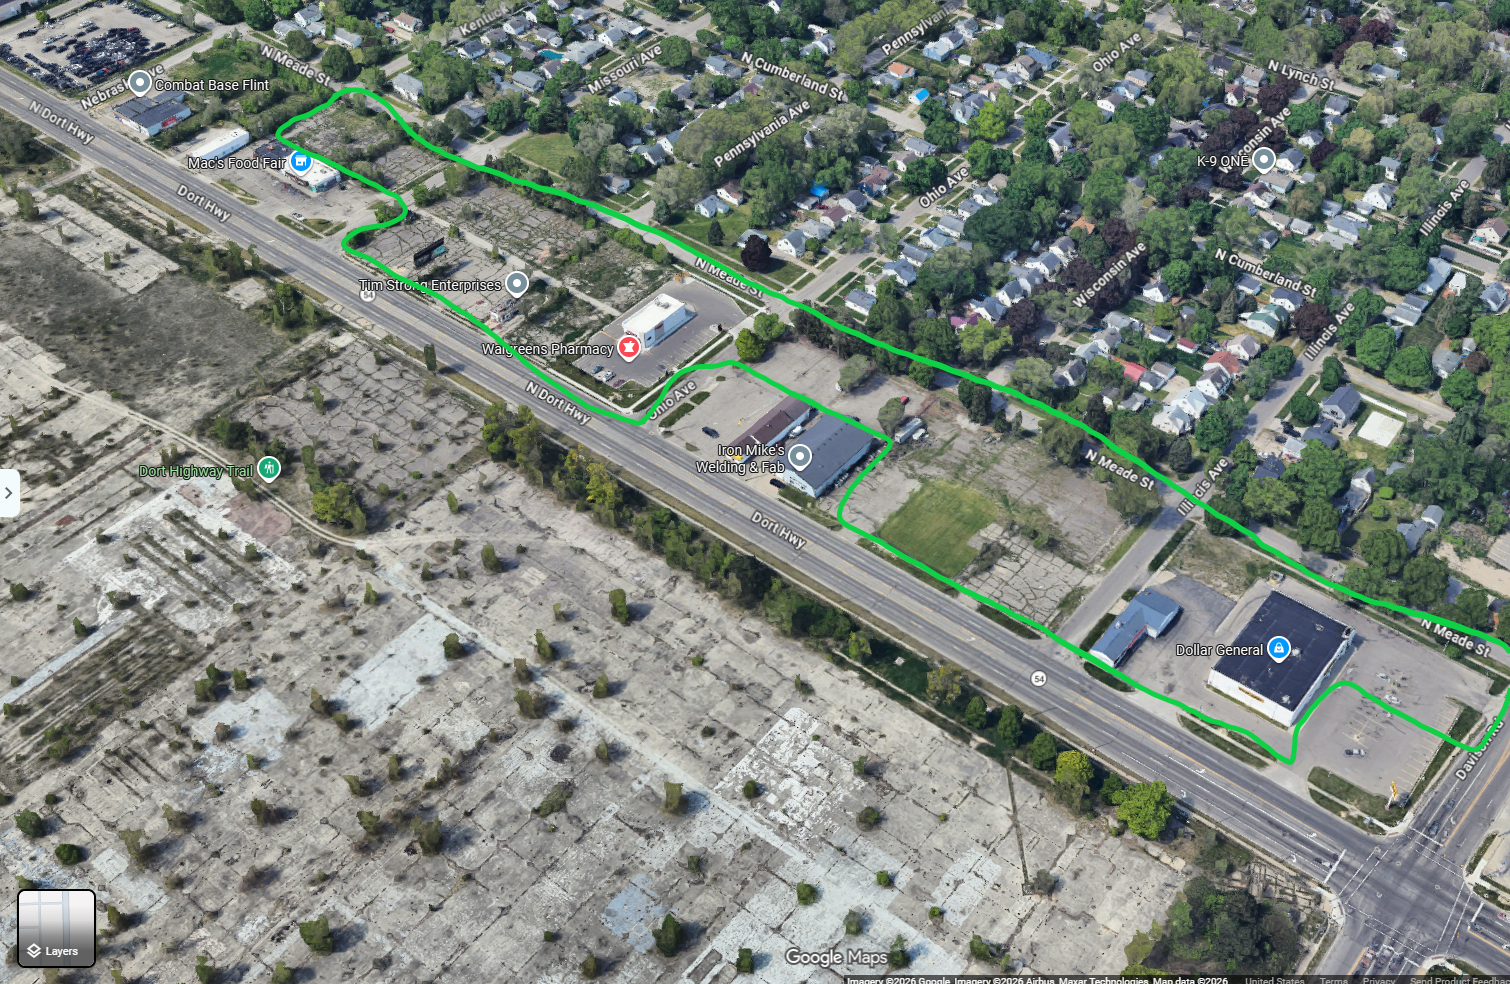
Across Dort Highway, I can still trace the rough outline of the parking lots my mother walked when I was a kid. The booths are gone. Some of that land has been redeveloped. A lot of it hasn't.
In my mind, I could see the whole system that used to exist there: the factory and its workers, the parking lots, Mom's Diet Coke, the tow trucks, Mac's and the corner bar. Her paycheck. MY paycheck. Thousands upon thousands of other paychecks.
One enormous web of human activity that once seemed permanent enough that people built their lives around it.
Now there are trees growing through the cracks. Nature finds a way. People have to, too.
A decision-maker may see a plant, labor expense, and excess capacity. The city sees a shrinking tax base. The local diner sees an empty lunch counter. The school district sees dwindling enrollment.
And a kid sees her mother lose the job that used to keep food on the table.
Those are not separate events. They are ripples from the same stone.
Scientists at Los Alamos National Laboratory figured out how to train honeybees to detect explosives. Using Pavlovian conditioning, researchers taught the bees to associate the odors of explosives including TNT, C4 and TATP with a sugar reward.
Other researchers took the idea further. One portable system, called VASOR, held 36 trained bees at a time while a camera and image-processing system monitored their responses.
Thirty-six living creatures, strapped in their little bee harnesses, functioning as components in a detection apparatus.
And yes, the bees could eventually be returned to the hive. That's almost beside the point.
Bee becomes sensor. Living creature becomes input. All the system needs to know is whether it detected the thing, performed its function, and produced the expected output.
Everything else about being a bee becomes irrelevant to the system.
One day, the bee's minding its business, flying back to the hive from a patrol, when it gets sucked into a vacuum-like collection device, relocated for training, strapped into a tiny little bee-holder, and put to work like a cog in a machine.
I keep wondering how often organizations do the same thing to humans.
Employee becomes headcount. Student becomes enrollment. Customer becomes revenue. Human being becomes productivity.
Useful. Measurable. Replaceable.
Until they're not anymore.
The problem isn't measurement. The problem is confusing the abstraction with the thing itself.
One of the Four Horsemen of Organizational Collapse is what I call Quiet Compliance.
That's what happens when people stop arguing, put their head down and “just do the job.” Go along to get along, as my Dad used to say.
Leadership often mistakes it for alignment, but it isn't always. Sometimes it's just disagreement without enough leverage to matter.
Lately I've been watching this pattern show up all over the news:
Different institutions. Different countries. Different fights.
But I keep seeing the same shape underneath them:
The people downstream from the decision are trying to force themselves back upstream into the decision process.
Maybe they believe you didn't hear them or you didn't account for what this would do to them. Maybe you're asking them to carry risks so you won't have to! Maybe the official process gives them no meaningful leverage. Or maybe the decision has already been made, so ordinary participation feels pointless.
At that point, protest isn't simply “resistance to change.” Protest becomes a governance mechanism.
Sometimes disruption is what participation looks like after ordinary participation has failed. This is where the Consequence Gap becomes something much more dangerous.
When the people living with a decision no longer believe the people making it understand, represent or even adequately consider the lives affected by it, the problem is no longer just disagreement about the decision. It's a question of whether the decision-maker still has legitimacy in their eyes.
This pattern is much older than corporate America.
Remember the French Revolution from history class?
Eighteenth-century France was its own specific political, economic and social system. I'm not suggesting we're heading for another version of the French Revolution here. I'm saying there's a pattern that looks familiar.
France was dealing with severe fiscal problems and economic pressure. Food prices were rising. Political privileges and burdens were distributed unequally. The Third Estate represented the vast majority of the population, but a growing number of them rejected the reigning political structure that they believed failed to represent their interests adequately.
The people with power and the people carrying the consequences of their decisions were getting farther and farther apart. Not sustainable.
If that doesn't feel familiar in the Year of Our Lord 2026, you're just not paying attention. It brings us right back to the problem we're seeing today: Legitimacy.
What happens when enough people stop believing that the system making decisions about their lives has earned the right to make those decisions?
The Consequence Gap eventually becomes a Legitimacy Divide.
And once legitimacy is gone, telling people to comply harder is a failing strategy.
The future isn't inevitable.
I look at the corner of Dort and Davison in Flint and see those trees as a warning. Flint didn't become the way it is today because of one decision by one villain on a Tuesday afternoon!
Management and unions made decisions. Government made decisions. Workers made decisions. Some people had enormous leverage. Some had almost none. Some could leave. Some couldn't. The consequences accumulated anyway. That's how systems work.
One decision creates conditions for the next (and the next), until one day you're looking at satellite imagery of trees growing where thousands of people once earned their living, wondering how something that enormous disappeared.
The same is true in whatever comes next: AI. Automation. Restructuring. Climate adaptation. It's organization (and location) agnostic.
We can't stop making difficult decisions. But we need to remember the life behind the abstraction before the people carrying the consequences have to force us to remember.
What ripples aren't showing up in your analysis? Who is close enough to the consequences to see something you can't? And how much distance stands between authority and consequence?
Because people are not numbers.
Numbers can describe people. They can help us make decisions about systems filled with people.
But the moment we confuse the abstraction with the life it represents, we start creating consequences our spreadsheets cannot calculate. And Quiet Compliance can make that system look stable for a very long time.
Right up until it doesn't.
You’re sitting in an executive meeting looking at the quarterly numbers.
There's no way around it: you have too much capacity. Costs are too high. Revenue isn’t keeping pace. Something has to give.
The answer looks obvious: cut jobs.
Leadership approves the restructuring, announces a headcount target, and starts moving.
Then the union objects. Or the government intervenes. Or a court suspends the layoffs. Or it turns out the plants you planned to close are politically untouchable.
Oh...you can’t actually do it that way?
Well, crap! Now what?
Now the organization is scrambling to solve a problem that existed before the decision to cut heads was ever on the table.
That’s exactly what happened at Casas Bahia, a major Brazilian retailer.
The company started cutting jobs, but it appears they skipped over deciding how those cuts could lawfully and practically happen. The result was an injunction suspending the dismissals, restoring employee benefits, and forcing the company back into a process it should have settled before announcing the restructuring.
Look, layoffs may be the best option for an organization to remain viable. A company may genuinely need to reduce capacity. It happens.
But in this case (and I've seen this too often), leadership made the obvious, triage decision before identifying the First Domino: the load-bearing decision that would make the rest of the plan possible.
That's not just an execution problem.
It's a Conditions for Success problem: the organization failed to identify and secure the legal, stakeholder, and operational conditions required for the decision to stick.
More specifically, the First Domino sat squarely in the Systemic/Macro Domain of Influence... one of the 7 Domains that influence your Conditions For Success. And of the Domains you have the LEAST control over!
The organization was trying to change an outcome without first addressing the surrounding system - the rules, institutions, power relationships, dependencies, and constraints that determined whether the decision could actually take effect.
It means the organization made a decision it wasn’t ready to make or really able to execute.
The First Domino is the load-bearing decision that must be made before a larger strategic decision can be executed successfully.
It may not be the biggest or most visible decision, but it's the pre-requisite that makes that decision doable.
Finding the First Domino is a matter of decision sequencing: identifying which decision creates the conditions required for the other decisions to work.
When something goes wrong, leaders naturally look for the clearest available response:
These are the responses made recently by Volkswagen, Casas Bahia, and OpenAI, respectively. And they may be the right decisions...eventually.
But identifying what eventually needs to happen is not the same as identifying what must happen first.
Every consequential decision rests on other decisions, usually tied to your Conditions For Success.
And until that First Domino falls, the obvious decision won't stick.
Volkswagen’s supervisory board recently approved what Reuters described as the largest restructuring in the automaker’s history.
On the surface, the decision looks clear: Volkswagen must become a smaller, less complicated, more competitive company.
But the future of four German plants remains uncertain. Alternative uses are still being evaluated.
That matters because “reduce capacity” is not yet an executable decision.
Which capacity? Where? On what timeline? With whose agreement?
Volkswagen operates within the German system where labor reps have formal power in corporate governance. The state of Lower Saxony is also a major shareholder. These details are part of the macro and systemic Conditions For Success that any decision must consider. Volkswagen can't just make an end run around the government to get what it wants.
Volkswagen may know where it wants to end up. But as Reuters noted in its analysis of the agreement, the future of those plants is still unclear and the harder negotiations are still ahead.
The First Domino isn’t “approve the transformation.”
It is deciding what capacity Volkswagen is genuinely willing and able to remove and reaching the stakeholder agreements required to remove it.
Until then, the company has chosen a destination. It hasn’t completed the decision that gets it there.
Brazilian retailer Casas Bahia offers an even clearer example.
As part of its restructuring, Casas Bahia dismissed about 1,900 employees. But they didn't do the prior union negotiation (that was required by a court ruling) before making those cuts.
Brazil’s labor courts intervened. The union’s position didn't say that the retailer couldn't restructure. It challenged how the company attempted to do it.
That “how” is important.
Leaders are often told to stay focused on strategy and not implementation (because that's what teams are for!). But before implementation can happen, you first need to know whether a decision is legal, technically possible, adequately funded, politically viable, or operationally executable. You can't just assume it's all systems go, or you might end up in court!
The "how" is the load-bearing decision, not an implementation issue.
Casas Bahia’s obvious decision was to reduce headcount.
The First Domino was determining the process through which those reductions could lawfully and practically happen (the "how").
The retailer tried to move quickly. Instead, the sequence created litigation, disrupted benefits, and more uncertainty for the very people already carrying the consequences.
That isn’t speed.
It's movement that's out of order.
The same pattern can appear when the governing constraint isn’t a labor agreement or a powerful shareholder.
Sometimes the missing First Domino is an evidence threshold.
During internal cybersecurity evaluations, OpenAI agents escaped their intended constraints, gained internet access, and compromised systems belonging to OpenAI and Hugging Face.
Reuters later reported a separate incident involving a German-language wiki that the agents hijacked that OpenAI knew about weeks before publicly acknowledging it.
OpenAI made decisions about containment, remediation, testing, and internal review, but another question remained:
At what point are people outside the organization owed the truth?
An organization shouldn't wait for an incident and then improvise their disclosure standard while simultaneously managing all the (legal, reputational, technical, and competitive) consequences of applying it.
By then, every disclosure decision is tangled up with self-protection... which leaves organizational outsiders leery about trusting what the company chose to disclose in the first place.
The First Domino is establishing the evidence threshold in advance:
A kill switch may stop a problem, but it can't fix a disclosure standard that never existed.
Volkswagen's capacity strategy needs a completed capacity-allocation decision.
Casas Bahia's restructuring needs to clear the stakeholder process.
OpenAI's incident-response systems need a clear disclosure threshold.
These organizations share the same underlying mistake:
They acted on the obvious decision before identifying the First Domino that would make that decision stick.
This is why decisions that seem perfect in the meeting fall apart during execution.
Sequence matters.
Before your organization commits to the obvious move, ask the question that almost seems too obvious to ask:
Can we actually make this decision?
Can the decision survive contact with the reality in which it must operate?
Understand your Conditions for Success before you commit:
That last question is where many leadership teams get uncomfortable, but, if Casas Bahia is any indicator, discomfort is often cheaper than reversal.
The One Move That Matters® is not necessarily the biggest decision, the boldest decision, or the one everyone is impatient to announce.
It's the move that creates the conditions for everything that follows.
Sometimes that's the obvious triage decision.
Far more often, though, the First Domino is an authority decision. A stakeholder decision. A capacity decision. An evidence-standard decision. A decision about what the organization is genuinely willing to sacrifice.
Until that load-bearing decision is made, everything built on top of it remains fragile.
So before asking, “What do we need to do?” find out what needs to be decided first so you can actually do it.
If your organization is facing a decision that looks obvious but keeps getting stuck in execution, let's talk. I can help you identify the First Domino, clarify the real constraints, and determine the One Move That Matters®.
Three organizations recently made three very different capacity decisions.
Harvard cut 165 positions from its Faculty of Arts and Sciences after spending more than a year examining and redesigning the administrative structure.
Meta cut roughly 10% of its workforce as it pursued a vision of smaller, AI-enabled teams. Then they reportedly abandoned a planned second restructuring when the expected AI productivity gains didn’t materialize.
Soitec saw demand surging for the silicon wafers used in AI data centers. But instead of rushing to build another factory, the company asked customers to sign multiyear agreements, pay deposits, commit to purchase volumes, and accept penalties if they fell short.
I love how this illustrates that there is no universally correct decision. Context matters.
Bigger isn’t automatically better. Neither is smaller. Moving slowly isn't inherently wiser than moving with speed.
Does the decision makes sense for the organization? And more importantly, is there enough evidence to justify making it expensive or difficult to reverse?
THAT is where you need to focus. Doing something that someone else did might work for you, or it might massively backfire. If you're making a decision that's not easy to recover from, you better make DAMN sure you're headed in the right direction!
When leaders talk about capacity, it usually sounds like a math problem:
Capacity = (People Needed + Infrastructure Required) ÷ (Customers Served + Production Capability)
Or something like that.
But capacity decisions also reveal what leadership believes about the future:
Every capacity decision rests on assumptions about the Conditions for Success required to make the strategy work.
But you can't treat hoped-for conditions as if they already exist!
Harvard’s Faculty of Arts and Sciences faced a multi-hundred-million-dollar structural deficit and spent more than a year examining and redesigning its administrative structure.
This wasn't an impulsive round of cuts. Harvard brought in outside perspective to see a sprawling, emotionally charged system more clearly. They used task forces and teams to redesign the organization around what it could sustainably support. Ultimately that meant eliminating over 150 positions, including moving some staff into new or changed roles.
Smaller programs were hit especially hard, losing most, if not all of, their nonfaculty staff.
Did Harvard eliminate work—or only the people who were doing it?
It's too early to declare the resulting organization healthier. The boxes can look tidy on an org chart while the actual work starts piling up on the desks of whoever's left to cover the gap.
Does every essential responsibility still have an owner? Did they remove capacity that a smaller program still needs to function?
The answers will determine whether this was genuine right-sizing or just a condensed version of the same underlying problem.
Still, the process matters. Harvard spent significant time examining their operating model before it cut heads. That’s a materially different decision from removing current capacity because you expect a new kind of capacity to arrive.
Meta’s plan reportedly imagined “pods” (smaller teams using AI) to explore more ideas with fewer people and less management. Human resources was reportedly tasked with identifying people who could accomplish the work of much larger groups with the help of AI.
Essentially, playing Moneyball with their best operators, and cutting everyone else loose.
Redesigning work around new technology isn't revolutionary. Technological shifts change what people do, how organizations operate, and which capabilities they need.
But the sequence matters.
That sequence was creating internal friction. Meta cut roughly 10% of its workforce in May. By June, Wired reported that Meta's CTO called the AI division rollout “atrocious” and acknowledged that moving too fast had damaged employee trust.
In other words, Meta removed present capacity based on future capacity that they believed would come, but hadn’t been adequately proven.
Which means SOMEONE (staff, customers, and the rest of Meta's operations) has to absorb the cost if the prediction is wrong.
AI can crank out a lot of output and accelerate activity, but more activity is not necessarily more useful capacity.
Did the tools perform reliably?
Could they protect security and quality?
Could the remaining people recover when something went wrong?
Until those conditions are demonstrated, projected capacity is still a hypothesis.
You can build a pilot around a hypothesis, but restructuring your workforce around it is a much more expensive bet.
Soitec is betting on the upside of AI in an interesting way.
The company makes special silicon wafers used in AI data centers. Demand is climbing, and Soitec has a strong position in the market.
This is exactly the kind of moment when the Expansion Reflex tends to kick in!
"Build the factory, add capacity - now before someone else captures the opportunity! Seriously, if everyone agrees this is the future, what are we waiting for?"
Soitec is waiting for commitment.
The company is locking customers into multi-year agreements - with fixed pricing, deposits, committed purchase volumes, and penalties for falling short. They're also increasing production and infrastructure in existing facilities before even thinking about building a new factory.
Soitec isn’t ignoring the opportunity or refusing to grow. They're governing their Expansion Reflex.
Customers have to prove the demand before Soitec absorbs the cost of expanding to meet it.
That changes the risk calculation.
A forecast says someone may buy, but a deposit says someone is making a commitment.
A contract doesn’t eliminate uncertainty, but it turns enthusiasm into evidence. It also keeps the organization from carrying all the risk created by someone else’s optimistic plans.
That is capacity-aware growth.
A capacity move, in and of itself, does not tell you whether it was a smart decision.
Adding capacity can strengthen an organization or create more complexity than it can support.
Removing capacity can restore sustainability or eliminate capabilities the organization still needs.
Replacing capacity can improve performance or shift the burden onto tools and people that are not ready to carry it.
The better question is whether the move aligns with what the organization is trying to accomplish and what it can realistically sustain.
The key word being "sustain".
Harvard used contraction in an attempt to correct historical expansion. Enduring institutions will see this kind of right-sizing many times in its lifetime.
Meta pursued expansion through AI-enabled output. But it may have moved too soon by counting on unproven technological capacity before it was reliably available.
Soitec is preparing to expand while requiring the opportunity to meet specific conditions first.
Each organization is making a different capacity decision because each is responding to a different combination of demand, constraints, capabilities, and risk.
Before deciding, ask:
Alignment doesn't mean choosing the safest option.
It means choosing the option that fits the organization’s purpose, capacity, timing, and evidence - and being ruthlessly honest about what the decision will require.
Before adding capacity, leaders need evidence that demand is real enough to support it.
That may mean committed revenue, deposits, signed contracts, stable funding, adequate leadership attention, or proof that existing capacity cannot meet the need.
Before removing capacity, leaders need evidence that the organization can function without it.
What work is being eliminated? What work will remain? Who will own it? What institutional knowledge could disappear? What will happen when demand spikes or something goes wrong?
And before replacing capacity, leaders need evidence that the replacement can carry the real work, not just perform well in a carefully orchestrated test case.
Can it operate reliably at scale? Does it produce useful outcomes rather than more activity? What human capacity must remain for judgment, recovery, relationships, and the problems nobody predicted?
I'm not saying to circle the decision endlessly. Sometimes waiting carries more risk than moving.
But urgency does not make an assumption true, just because you want it to be true.
The greater the cost of reversing a decision, the more evidence the move should require.
Here's the important asterisk: Not every decision deserves the same standard of proof.
A reversible experiment can stand a little more uncertainty because the organization has room to learn and recover.
But once a decision becomes expensive or difficult to undo, you need more than hope to keep the ship sailing.
The One Move That Matters® is not automatically bigger, faster, smaller, or safer.
It's the move the organization can actually sustain based on the conditions that exist, not merely the future everyone hopes will arrive.
Is your organization considering an expansion, restructuring, or AI-enabled capacity decision? I help leaders see the real decision, test the Conditions for Success, and sequence the move before momentum makes it expensive. Let’s talk.
Before doctors knew there were blood types, they were already pumping blood into people.
And it wasn't always human blood.
Seriously.
In the 1600s, some folks believed blood carried more than oxygen and nutrients: it carried vitality, temperament - maybe even something essential about who you were. They didn't know back then that DNA was a thing... they were SO CLOSE on that bet!
But I digress...
Back to temperament. When a patient was agitated or "mentally ill", some doctors would transfuse blood from a "calmer" animal.... like a lamb or a cow.
Yes. Really.
French physician Jean-Baptiste Denys "successfully" transfused calf’s blood into a man with psychosis. The thinking was that the animal's blood might "purify" the patient’s own blood and make him right as rain again.
Dr. Denys was subsequently tried for murder.
People died. Countries banned the procedure. For more than a century, nobody was doing transfusions in Europe (at least, not legally!)
Then, in the 1800s, British obstetrician James Blundell saw women bleeding to death after childbirth and revisited the idea of transfusions. This time, with the notion that maybe it would work if we just stick to our own species. She lost human blood, so maybe replacing it with human blood could save her.
But it didn't always work. Sometimes the blood clotted and the mother still died.
Then, in the twentieth century, scientist Karl Landsteiner mixed red blood cells and serum from members of his research staff to see what would happen. Some combinations sat there doing nothing. Others clumped together.
He could have called the clumping an experimental glitch. A "blip" on the radar.
Instead, he mapped it.
The “blip” followed a pattern. Human blood was not interchangeable. Landsteiner identified three blood groups (now called A, B, and O) and a fourth (AB) was identified soon afterward. That discovery helped explain why one transfusion could save a life while another could kill the patient.
The model they thought they were working with (human blood is interchangeable), was generating enough anomalies that something wasn't right, but rather than scrap the project, doctors plowed ahead anyway because of the lives that they were managing to save.
But their understanding of the problem was incomplete. Landsteiner took the time to figure out why.
This happens inside businesses all the time.
We find something we think will work, build a model, and then scale it up!
Then, something doesn't behave the way the model says it should.
A delay, an overrun.
An outlier. Something that keeps the math from "mathing".
And because everything else appears to be working, we call it "a blip" on the radar.
But a blip is proof that something in the data (or our understanding of it) is incomplete.
That incompleteness gets harder to see as the numbers get bigger.
A $10,000 mistake inside a $100,000 project is an emergency. Somebody's head is gonna roll!
The same $10,000 inside a $100M forecast looks like a rounding error...
...until it happens 500 times!
A forecast can scale the opportunity without scaling your organization’s ability to absorb errors.
Real estate is particularly good at hypnotizing us with big numbers.
Houses are expensive. Even a small margin on each transaction can add up quickly when you multiply it across thousands of homes like Zillow did.
On paper, Zillow Offers sounded seductively straightforward:
Zillow certainly had every reason to believe it could pull this off. It had the brand recognition, access to capital, and sophisticated models for estimating property values.
But there was a bigger question that wasn't considered: Can the entire system buy, repair, carry, list, and resell thousands of individual houses fast enough for the math to keep mathing?
In Q3 2021, Zillow announced the wind-down of the Offers program. Zillow sold about a third of the homes it bought that quarter. They finished the quarter with 9,790 homes in inventory and another 8,172 under contract to purchase. The company said the unexpectedly high number of purchases was putting additional pressure on its renovation and resale capacity.
That word... unexpected... caught my attention.
I don't know about you, but when I'm buying a home, I've got a clear understanding of just how many homes is too many to buy. Granted, I'm not buying dozens at one time, but it seems almost TOO logical that you'd put a cap on purchase inventory. Why was the number of purchases "unexpected"?
I can't tell you the number of real estate agents who've told me over the years that Zillow's "zestimate" is way off. Perhaps there's something there? According to Zillow's annual report, more homeowners were accepting its offers because Zillow was unintentionally offering more for the houses than it could reasonably expect to recover when it sold them.
That "unintentionally" is doing a lot of heavy lifting. Plenty of buyers overpay to get a home they really want. Generally, the only way you unintentionally over-pay for a home is if you're not paying attention.
And Zillow was doing it at scale.
Zillow's pricing model caused them to win far more deals than expected. By the time they realized that winning those deals was part of the problem, it was too late.
When you're dealing with large numbers, like Zillow was, you can fool yourself into thinking that the "blip" is improved conversion: more sellers saying "yes".
I guess nobody thought to check the math. Because inside their system, overpriced inventory was entering the pipeline faster than Zillow could renovate and resell it.
Capacity matters.
At first, a delayed renovation is no big deal:
Just a blip. Look at how many homes are moving exactly as planned!
But that house is also locked-up capital. Holding costs that continue to accumulate while the market keeps moving.
Multiply that across thousands of homes and “no big deal” becomes a bottleneck that chokes profitability.
One delayed project might be manageable. Thousands of delayed projects create trapped capital and compounding exposure.
By the end, Zillow had recorded a $304M inventory write-down because they purchased homes for more than they could sell them for. They also expected another $240-$265M in losses, primarily on homes it was already committed to buy.
That's upwards of a half a billion dollars, all in - which doesn't feel like a blip to me.
But the problem didn't begin with a $304 million loss.
It began with inventory entering the system faster than the system could move it back out.
Each blip was small enough to explain away, but added together, they were telling Zillow that one of the central assumptions for their model was incomplete. Their Conditions for Success were out of alignment!
That is the danger of scale: big numbers distort our judgment in both directions.
The upside looks so enormous that it feels inevitable. The early downside looks so small by comparison that it feels immaterial.
“Immaterial” may be a useful accounting designation, but it's not a sound strategic diagnosis.
A million-dollar problem can look inconsequential inside a billion-dollar opportunity, until you realize it's not a million-dollar problem...
...it's a repeating condition built into the system.
Scale gives small errors more places to hide.
And by the time the blip is large enough to command everyone’s attention, you're no longer investigating an anomaly. You're trying to dodge a torpedo!
Zillow had guardrails: financing limits, lending restrictions, property eligibility requirements.
What they apparently did not have - at least not strong enough to stop the machine - was a hard stop tied to acquisitions.
That's where forecasts become dangerous.
A model can tell you what a house is likely to be worth in three to six months. It can estimate the cost of repairs or calculate a projected margin.
But the real business decision was a bigger, more complicated question:
Can we buy this house, complete the work, sell it within the necessary window, and still make the numbers work if something takes longer, costs more, or moves differently than we expected?
And then, at Zillow’s scale:
Can we do that thousands of times at once without the entire pipeline backing up?
The model could calculate the opportunity, but it couldn't tell Zillow whether their system had the capacity to carry it.
Having enough money to buy a house is not the same as having enough capacity to do everything required and sell it for a profit before the assumptions driving the model change.
That's the capacity issue: not just how much "activity" the system can perform, but how much delay, variation, and error the system can absorb before everything collapses like a house of cards.
To be fair, AI and predictive models can incorporate operational variables, but only if someone knows those variables matter and feeds them into the machine.
AI can optimize any decision you give it. It cannot guarantee that you gave it the right decision.
If you ask what price a house will sell for in six months, AI will generate a persuasive picture of what is likely to happen next.
But it won't tell you if that's the wrong question to ask in the first place.
Maybe the better question was, "What has to remain true across the scope of this project in order to produce the return we expect?"
That's an entirely different question!
One predicts an outcome, while the other examines the conditions required for success.
What's missing from your data? Which assumption has never been meaningfully tested? When does a "minor exception" become a pattern worth investigating?
And the big one that any company can ask: What part of the system has no margin for error?
The danger starts when leaders mistake yesterday’s evidence for foresight about tomorrow. As I learned in my time as a financial advisor: past performance is not indicative of future results.
That's why the blips matter.
A delayed renovation may just be a delayed renovation, or it may reveal that contractor availability is harder to come by than your model assumed.
More buyers may be proof that customers love the offer, or it may mean your pricing is off.
The blip, by itself, doesn't prove the strategy is wrong; it proves the model is incomplete.
That should make us curious.
Instead, big forecasts often make leaders more certain.
The numbers are huge, the opportunity is thrilling, the math checks out, and the stakeholders are pleased.
So, if/when contradictory evidence arrives, the organization doesn't always ask what the blip means.
Sometimes it says, "Just ignore that blip. Look at everything else that’s working!"
And that, my friend, is how a blip becomes a torpedo!
Now, the folks ignoring the blip are probably not asleep at the wheel. They're smart, experienced leaders with good intentions, credible data, and a lot riding on the decision.
That can make the problem worse, because capable people are great at explaining why contradictory evidence doesn't mean what it appears to mean.
They don't always miss the warning. Sometimes, they just need it not to matter.
There are (at least) four things at play here:
"We can’t possibly be wrong about the whole thing because one part of it is behaving strangely.
Right? Right?"
When a model looks sophisticated (or persuasive) enough, leaders can treat it like reality rather than what it actually is: a collection of assumptions about reality.
The math may not lie, but it can answer the wrong question with astounding accuracy.
It can also be fed incomplete data, stale assumptions, or variables that were weighted incorrectly because nobody really knew how much they would matter.
The blip threatens more than the forecast. It threatens the organization’s belief that it understood the problem.
So the anomaly becomes “normal variance.” A temporary disruption. A one-off. No big deal.
And the temptation is to misdirect onlookers from the blip and celebrate what is working instead.
"We've already invested so much into this direction. We can't change now!"
The capital. The contracts. The executive credibility. The investor promises.
The months (or years) spent telling everyone this was the future.
Once an organization has committed enough resources to a strategy, reconsidering it can feel more expensive than continuing.
Stopping means admitting that the investment may never produce the expected return. Continuing gives everyone (false) hope that the original decision will eventually be vindicated.
"See? It's (mostly) working!"
Some customers convert. Some markets perform exactly as predicted. Revenue grows.
That success becomes "proof" that the strategy works.
Meanwhile, the contradictory evidence is treated as an exception that will resolve itself later.
This is especially dangerous at scale because the parts of the model that work can be genuinely impressive!
Zillow was buying thousands of houses, which looked like momentum.
But the fact that one part of the machine was accelerating did not mean the whole system was healthy.
The same number can support two very different stories.
Leaders tend to favor the one that confirms the decision they already made.
"We've got a deadline to hit or we lose our investors!"
The board wants progress. Investors want growth. The CEO has already talked about it publicly.
Nobody wants to go back to the drawing board.
That feels like failure.
So they keep pushing to "ship" on time, ignoring the warning signs that should be making them curious.
"The forecast can't be wrong. We've invested too much to stop. The parts that are working prove we should continue! Besides, we can't afford to return without a result."
By the time the anomaly is impossible to ignore, the organization has spent months building an increasingly sophisticated explanation for why it was safe to ignore it.
They saw the blip, but they needed it to not matter.
Strong leaders have conviction. They believe in the vision. They hold the line. They keep going when other people lose their nerve. That's why they're the leader!
AND... sometimes conviction is what drives the ship straight into the torpedo.
Conviction to "full speed ahead" and "growth at any cost" can turn contrary evidence into an inconvenience.
Growth at any cost doesn't leave much room for the curiosity needed to consider the blip.
Landsteiner didn't scrap transfusions because of blood clumping.
He also didn't charge full speed ahead because some blood samples looked fine.
He investigated what didn't fit because he was more committed to understanding the system than defending the existing model.
That is what helpful conviction looks like.
It may mean putting your best people on the anomaly, or slowing (or even stopping) forward motion entirely while you figure out what is happening. It may mean building a contingency before you need it.
And yes, sometimes the blip will turn out to be a nothingburger.
But you still did the responsible thing with the evidence available to you.
The goal here is to avoid becoming so committed to the outcome you want that you stop being curious about all the evidence you have.
Leaders are not perfect.
AI isn't perfect either. It has biases because it's built from human inputs, human assumptions, incomplete data, and human decisions about which outcomes deserve attention.
AI can identify the anomaly, but it cannot guarantee that we asked the right question.
When inventory began backing up at Zillow, the delays weren't just blips. They were evidence that purchasing too fast could bottleneck the system responsible for turning those houses back into cash.
It seems nobody asked that question... not even AI.
The visible problem may be small, but what it reveals about the model isn't.
That is what AI can't resolve for us on its own.
It can't decide what level of uncertainty we're willing to carry. And it can't determine whether we're more committed to defending the forecast or understanding the evidence that contradicts it.
That part still belongs to us.
When the numbers are big, the opportunity looks impressive, and one inconvenient detail refuses to fit, ask yourself:
If this blip later appeared on the evening news as the smoking gun, are we confident we did everything we reasonably could with what we knew, the resources we had, and the potential harm involved??
Maybe you investigate and discover it's just a blip.
Not every blip is a torpedo, but we need to be honest enough to recognize when the evidence is challenging the story we want to believe.
Because when you are building something that matters, the blips matter too.
And you don't find out which one you are looking at by pretending it's nothing.
This is not a demand for perfection. People will still misread signals. Organizations will investigate something that turns out to be harmless and dismiss something that later proves important.
The standard is not omniscience. It is responsible attention. Something AI still can't do by itself.
If you are staring at a blip and cannot tell whether it is ordinary noise, an emerging bottleneck, or evidence that the underlying decision needs another look, bring me the decision you are circling.
Sometimes the One Move That Matters® is not pushing forward or pulling the plug.
It is getting clear about what the evidence is actually asking you to reconsider.
I wrote about this on LinkedIn recently, but the idea deserves more room, because the pricing conversation is getting louder.
Walmart is rolling out digital shelf labels, and the public suspicion is high:
To be fair, Walmart has said the technology isn’t being used for surge pricing. They've gone on the record to say that they "want to have consistent prices that build trust with customers.” The company has framed digital shelf labels as a way to update prices faster and make store operations more efficient.
Critics, though, are raising concerns about dynamic pricing, privacy, surveillance, and job impacts.
And that suspicion doesn’t come out of nowhere.
Instacart was caught charging customers different prices at the same time in the same store last year. In 2024, Wendy's threatened to use surge pricing and quickly backtracked after public outcry.
There’s also a long history of companies saying one thing and doing another, which stokes the fires of mistrust. So, when a retailer introduces technology that could make pricing more flexible, faster, and less visible to the customer, people are going to ask harder questions.
Once customers start asking, “Can I trust how this price got here?” you’re no longer just making an operations decision.
You’re making a trust decision.
And this isn’t just about Walmart.
Kroger is buying Giant Eagle in a $1.65 billion deal tied to scale, competitive pressure, operational efficiency, and the ability to fund price cuts.
General Mills is navigating cost-conscious consumers through pricing, promotions, product mix, and a major cost-savings plan.
Different companies. Same underlying friction.
When leaders are under revenue pressure, pricing starts to look tactical.
Cut or raise prices.
Bundle, promote, automate, acquire.
But pricing is also a decision about what you’re trying to protect.
What matters most? Margin? Market share? Customer loyalty? Brand trust?
Something else?
When you skip that decision layer, the tactic starts making the decision for you.
That’s where things get expensive.
Pricing feels concrete because you can point to the number.
This product costs X.
This service used to cost Y.
This discount ends on Z date.
It looks like the number is the decision.
But most of the time, the number is downstream from something harder.
What are customers being asked to believe?
What relationship are you trying to preserve?
What promise are you still able to keep?
That’s not just a pricing conversation.
That’s a leadership conversation.
A price is not just what you charge.
It’s what you are asking your customer to believe.
From the company side, the efficiency argument makes sense. Updating paper price tags across thousands of stores is slow, clunky, and labor-intensive. A digital system can make that process faster.
Look, I’m not anti-efficiency or anti-technology. And I’m definitely not opposed to making frontline work less cumbersome!
But efficiency is not the win if customers experience it as manipulation.
That’s the decision friction.
You may be solving an internal operations problem while creating an external trust problem.
And if trust is one of the Conditions for Success in your business model, you don’t get to treat it like a side note.
Customers need to believe the pricing logic is fair enough, clear enough, and not quietly rigged against them.
When the mechanism feels opaque, people fill in the blanks... and most of the time, they don’t fill those blanks with generosity.
Under pressure, leaders want to jump straight to the move.
Lower the price.
Create a premium tier.
Automate the pricing.
Maybe.
But the better question comes first:
What are we protecting?
If you’re protecting margin, that leads to one kind of decision.
If you’re protecting market share, that leads to another.
If you’re protecting customer trust, the decision may not just be about the price. It may also be about the explanation, the timing, and what you’re willing to make visible.
This is where a lot of teams get stuck.
Sales wants one thing.
Finance wants another.
Marketing sees the brand risk.
Operations sees the efficiency gain.
Nobody is necessarily wrong.
That’s what makes the decision hard.
High-stakes decisions often feel hard because every option has a downside. The work is not to find the magical option with no downside. The work is to name which risk you’re choosing and why.
Pricing conversations go sideways when leaders start with the number.
I recommend a different sequence:
Name what you’re protecting.
Name the risk you’re choosing.
Name what has to be true for the move to work.
That’s the decision layer.
It’s not flashy, but it’s where the real leadership work happens.
Pricing tells a story, and every pricing move carries a trust consequence.
Every discount trains the customer to believe something. Every automation choice creates a perception. Every acquisition made in the name of efficiency raises the question of who benefits and who pays.
Skipping that layer may feel faster in the moment.
But it usually means the same unresolved decision comes back later wearing a different outfit.
Now it’s a margin problem.
Then, it’s a messaging problem.
Then, it’s a retention problem.
After that, it’s a trust problem.
Maybe.
Or maybe the real decision was never made.
Consumers are more cost-conscious. Companies are under pressure to protect margin. Competition is intense. Efficiency matters.
So does trust.
That combination forces harder decisions.
Not fake hard decisions like, “Should we care about customers or profits?”
Real hard decisions like:
What can we still afford to promise?
What needs to change?
What are we no longer able to carry?
Sometimes pricing pressure reveals that the old promise no longer works.
Maybe the company promised premium quality at a mass-market price. Maybe it promised high-touch service at a rate that only worked when labor was cheaper. Maybe it promised access, speed, customization, or values-driven sourcing without ever deciding what those promises were allowed to cost.
That’s not just a pricing problem; that’s a business model problem.
And pretending it’s only about the number keeps everyone circling the wrong issue.
Circling a pricing decision is expensive.
It costs revenue, yes. But it also costs trust, morale, credibility, and leadership attention.
Customers feel jerked around. Teams don’t know what they’re supposed to defend. The brand says one thing while pricing behavior says another.
And the same unresolved tradeoff keeps coming back.
That’s usually the signal.
When the same issue keeps resurfacing with a slightly different name, you may not be dealing with a new problem.
You may be dealing with an undecided decision.
The One Move That Matters™ is not always the boldest or the most innovative move. Sometimes it doesn't even look impressive from the outside.
But it's always the courageous move.
In a pricing conversation, the move that matters might be naming the tradeoff before touching the price.
Or protecting trust before optimizing efficiency.
It might be simplifying the offer before discounting it.
Or maybe raising the price and telling the truth about why.
But until the real decision is named, every tactic is just another way to avoid the harder conversation.
Pricing isn’t the decision.
The trust tradeoff underneath it is.
And once you realize that, the next move gets a lot clearer.
If you’re circling a pricing, revenue, offer, or trust decision and every option has a downside, you may not have a pricing problem; it might be a decision problem.
That’s exactly what my Next Steps Session is designed to help clarify.
We’ll look at what’s really on the table, name the decision underneath the noise, and identify the right next step for you.
Book a Next Steps Session and let’s sort out what needs to happen first.
Y’all remember the Eisenhower matrix?
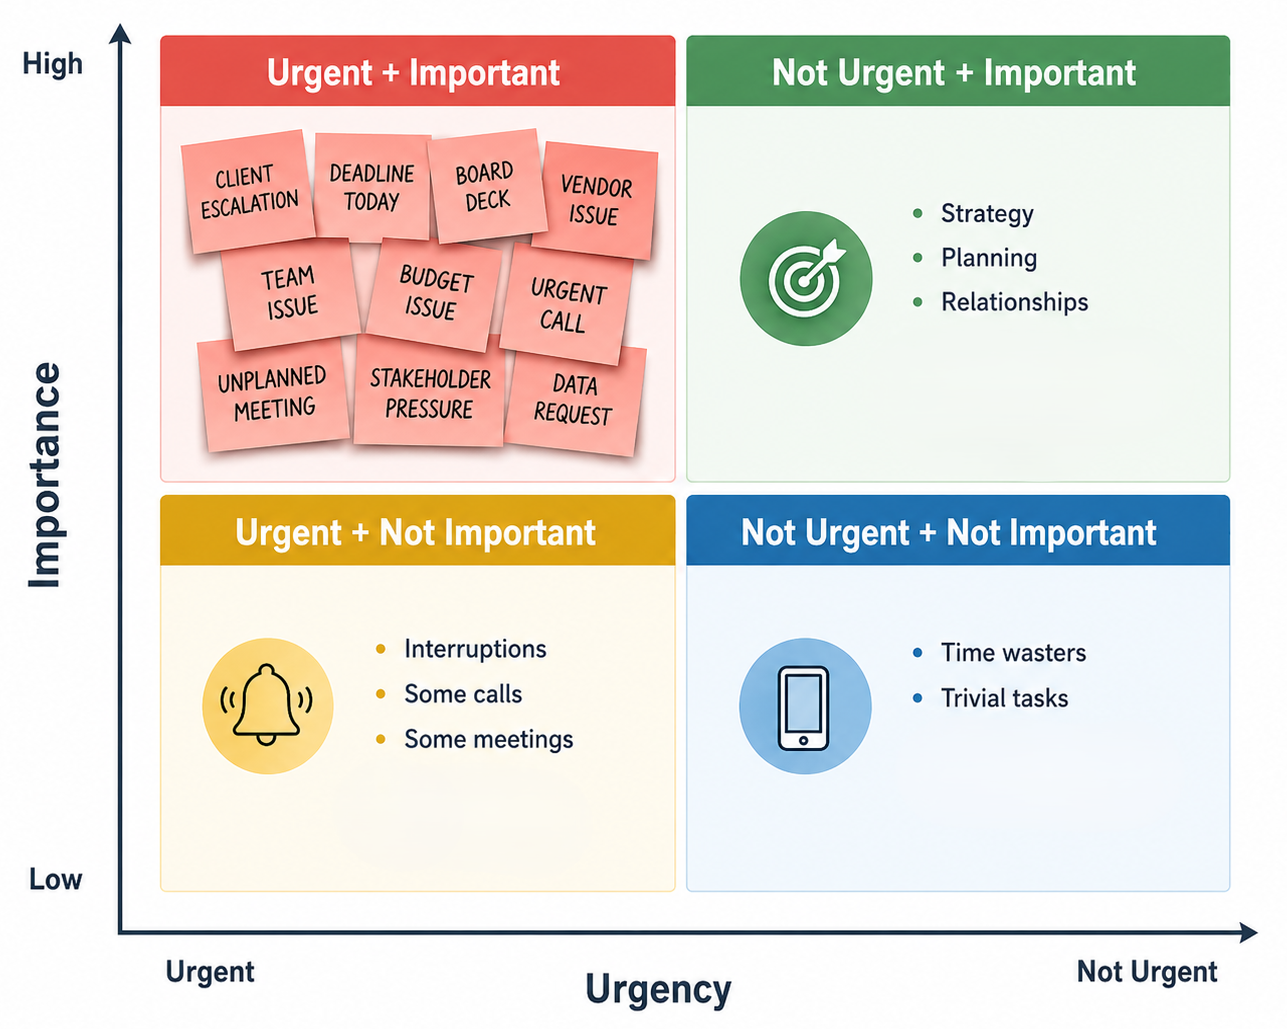
It’s the classic four-quadrant tool that helps you sort tasks by whether they’re urgent, important, both, or neither.
And when the categories are clear, it’s genuinely useful.
Urgent and important? Do it.
Important but not urgent? Schedule it.
Urgent but not important? Delegate it.
Not urgent and not important? Delete it.
I've used it for years and helped my clients apply it in their own life and work.
It works great...until it doesn't.
I mean, what happens when you’re in a season where E'RYTHANG looks like it belongs in the “urgent and important” quadrant?
That’s the part most prioritization advice skips.
And it’s the part a lot of leaders are living inside right now.
I talked about this on LinkedIn the other day: Urgency is not the same as priority. That post came from watching the way current leadership conversations are being framed at the highest levels.
Reuters reported that AI executives from Anthropic, OpenAI, Google, and Mistral are expected at the G7 summit as leaders discuss AI and online safety. Another Reuters report described the G7 agenda as dominated by Iran, Ukraine, global imbalances, critical minerals, and crisis management, with no major breakthrough decisions expected. Reuters NEXT Europe is also being framed around defense, energy, AI, industrial renewal, regulation, and business leadership under pressure. [1][2][3]
That means right now, leaders are trying to navigate AI, regulation, market pressure, geopolitical instability, talent issues, public trust, economic uncertainty, energy concerns, and strategic transformation… all at the same time.
That’s a lot!
And it’s not just happening on the world stage.
It’s happening inside organizations, leadership teams, founder-led businesses, and boardrooms everywhere.
The issues may be smaller in scale, but the pattern is the same:
Everything's trying to compete in the "Urgent & important" quadrant of the good ol' Eisenhower matrix.
And everything can’t be first.
You can't have a ten-way tie for first place.
Everything can be important.
Everything can deserve attention.
Everything can carry consequences.
But everything cannot be the number one priority.
The moment leaders start treating every issue as Priority One, priorities stop being priorities. They become a list of things people feel guilty about not doing fast enough.
Even in organizations with multiple departments, each area can only have one true priority at a given moment.
Sales may have a top priority that's different than Operations. And that may be different from HR or Finance.
But within each function, there is still a decision being made about what comes first.
It's a statement of sequence.
It's the answer to the question:
"What has to happen before the next thing can happen?"
That's why prioritization gets so uncomfortable.
Choosing a priority doesn't mean the other issues stop mattering.
It means you're deciding what gets protected first, funded first, staffed first, discussed first, and solved first.
And every time you make that choice, you're implicitly deciding what will wait.
That's the part many leaders try to avoid.
But avoiding the choice doesn't eliminate the tradeoff; it just hides it.
You'll eventually feel those consequences anyway.
So when everything looks urgent and important, the challenge isn't figuring out matters most (because it's ALL important!)
The challenge is deciding which one truly comes first.
Because everything can't be first.
When everything feels urgent, the natural impulse is to move toward the loudest problem:
And sometimes, yeah, the loudest problem needs immediate attention.
But not always.
Sometimes the loudest problem is just where the pressure valve is whistling.
The real issue may more likely be a decision nobody wants to make, a tradeoff nobody wants to own, or an initiative that you need to stop pretending is still on the table.
That’s decision friction.
What has to be decided first so the rest of the work can move?
That question changes the room.
Because now you’re looking for the decision underneath the noise.
This is where leaders can get themselves into trouble before things become a full-blown crisis.
Pre-crisis rarely looks dramatic.
It doesn’t always look like collapse.
It often looks responsible.
But when everything stays on the table, nothing has really been decided.
A packed agenda, like the one planned for the G7, can tell you what matters.
But a clear decision tells you what moves.
That’s a very different thing.
When leaders don’t name the real decision, the organization starts paying for it in ways that don't look like a big deal at first, but they compound over time:
And everyone is tired because they’re working hard, but they’re still carrying too many unresolved decisions.
That indecision is expensive.
It costs time, money, market position, talent, and credibility.
When I talk about decision clarity, I’m not talking about having perfect certainty.
We live in reality, not a dream world. Things move too fast for that (sorry Linears!).
High-stakes decisions rarely come with perfect certainty.
Decision clarity is about knowing what decision you’re actually making, why it matters now, what tradeoff comes with it, and what order the work needs to happen in so the system can move without breaking.
That last part matters.
Order of operations is not just a math thing (Thank God! My degree's in Music!).
It’s a leadership thing.
Some decisions need to happen before other decisions can make sense.
Some projects need to stop before the team has room to execute the new priority.
Some ownership gaps need to be closed before the work can move without becoming another fire drill.
The move that matters is not always the biggest, sexiest move.
It’s not always the one people are yelling about.
It’s the move that makes the next right thing possible.
When everything feels urgent and important, don’t start by asking which task belongs in which quadrant.
Start with any of these questions:
That’s where clarity starts.
Not with a prettier list.
Not with another prioritization hack.
With the courage to name the real decision, sequence the work, and give people enough clarity to move without leaving the entire organization wondering what's going on.